Prepaying Your Mortgage

jYsq5Z1vFEuCTCFozCD_Cg.jpg

Paying off your mortgage can provide peace of mind and is a worthy goal but is it the best thing for you to do at this time.

Do you have higher interest rate debt currently? If you have credit card debt with double-digit rates or personal, car or student loans, you’ll probably save more money from interest by paying these things off before you pay off your mortgage which is usually one of the lower rates on debt.

Many financial advisors recommend funding your annual retirement contribution before paying down a mortgage. If your company offers matching funds for your contribution, you would be leaving money on the table by not making the contribution to your retirement. For instance, you would be getting a $10,000 value by putting $5,000 into your retirement if your company matches it.

Creating an emergency fund is another favorite of financial advisors. When the rainy day arrives and you need funds, it may be difficult to get money from the equity of your home, especially if you have lost your job. Six months’ worth of living expenses is a good target to have available should you need it and a year’s worth would be even better.

Children’s college funds may be another priority that takes precedent overpaying off the mortgage. Whether you’re saving or investing to pay for their education, it is going to cost more than it did when you were in school.

When you are ready to start paying off your mortgage, decide on the best way to do it. Regular principal contributions on a monthly basis are very predictable and will get the job done. Setting up an automatic bill pay with your bank will assure that you don’t re-prioritize that extra amount every month because there is always going to be something else to do with extra money.

It is important to be sure that the lender applies the additional payment amounts to the principal and not to the escrow account.

Use the Refinance Analysis to see what extra amount you’d have to pay to retire your mortgage in a certain time frame or by making a specific additional amount each payment, you can find out when the loan will be paid. Regardless of which way you go, prepaying a loan will save interest, build equity and shorten the term on a fixed-rate mortgage.

Lower Your Cost of Housing

KFbeGPznYkiKr7jHr5m_Eg.jpg

Homeowners still have considerable advantages from the amortization of the mortgage and the appreciation enjoyed by most homes even with taking the standard deduction instead of itemizing to take the interest and property tax deduction.

There is an adage, “Rent or buy, you pay for the house you occupy.” You either pay for it yourself or for your landlord. The people who have job security, sufficient income, good credit and the funds for the down payment and closing costs can enjoy the many financial and emotional benefits of homeownership.

Looking at a $350,000 home purchased with an FHA mortgage with 3.5% down payment at 3.25% interest for 30-years, the total payment would be $2,420 a month. During the first year, the average monthly principal reduction is $573 a month which build the owner’s equity in the home.

At an estimated 3% appreciation, this home would increase in value at the rate of $875 a month during the first year which again builds the owner’s equity in the home.

Even if you consider the buyer will now be responsible for repairs and possibly homeowner’s association fees, the monthly net cost of housing in this example is $1,122 or less than half the monthly payment. The difference goes to equity which a tenant does not benefit from.

If the buyer were paying $2,750 monthly rent, they would be paying $1,628 more each month to rent than to own. In a year’s time, they would lose $19,500 of equity by continuing to rent. The down payment in this example is only $12,250 which would leave $7,000 to pay for buyer’s closing costs.

Purchase Price $350,000
Down Payment $12,250
Total Monthly Payment (PITI + MIP) $2,420
Less Monthly Principal Reduction (average first year) $573
Less Monthly Appreciation (average first year at 3% annually) $875
Plus Estimated Maintenance & HOA $175
Net Cost of Housing $1,122

The equity for the homeowner in this example at the end of seven years would be almost $140,000 based on the appreciation and amortization of the mortgage. Whether you rent or buy, you pay for the house you occupy.

Use this Rent vs. Own to plug in your own numbers for the price home you’d like to buy. If you need help with it, contact me and we can do it over the phone at (612) 532-4273 or in an online meeting.

Annual Advisory

SPDByXDwrUCnMxYDHCgNRw.jpg

Homeownership is a privilege and a responsibility. Even after decades of owning a home, you may still need some help to handle some of its challenges by focusing on the three “M”s of homeownership: maintenance, minimizing expenses and managing debt and risk.

While many people recognize the benefits of annual wellness, financial, vehicle and equipment maintenance visits, an important checkup that you may not have considered is an annual homeowner advisory or real estate review. Why would you treat the investment in your home with less care than you treat your car or your HVAC system?

Consider exploring the following:

  • Do you know the current value of your home? (You can, by obtaining a list of comparable sales in your immediate area, as well as what is currently on the market for sale.)
  • Have you compared your assessed value for tax purposes to the fair market value in order to possibly reduce your property taxes?
  • Even if you’ve refinanced in the last two years, can you save money and recapture the cost of refinancing in the length of time you plan to remain in your home?
  • Have you considered reducing your mortgage debt with low-earning cash reserves that will not be needed soon?
  • Do you have a record of the improvements you’ve made to your home since you purchased it? Do you know what items can be included?
  • Have you considered investing in rental homes in good neighborhoods to increase your yields and avoid the volatility of the stock market?
  • When was the last time you updated your home inventory of personal belongings? Do you have pictures as well as written documentation?
  • Do you need recommendations of repairmen and other service providers?

This service is part of my point of difference as a real estate professional to provide information to help homeowners not only when they buy and sell but all the years in between too. My goal is to create lifelong relationships with our customers as their “go to” person whenever they have a real estate question.

My strategy is to provide reliable, consumer-based information about homeownership on a regular basis through email and social networking. If it benefits you by helping you be a better homeowner, maybe you’ll consider us your real estate professional.

When you don’t know the answers to real estate questions, you know where to get them.

We’re always here to serve your real estate needs. By helping you with the three “M”s of homeownership, we can earn your confidence and trust for the next time you move or a friend of yours needs a recommendation.

If you’d like to have a list of the market activity in your area or any of the other information mentioned, please contact me at (612) 532-4273 or pam.howard

4 Reasons to Buy a Home This Winter!

4 Reasons to Buy A Home This Winter! | Simplifying The Market

4 Reasons to Buy A Home This Winter!

Here are four great reasons to consider buying a home today instead of waiting.

1. Prices Will Continue to Rise

CoreLogic’s latest Home Price Insight report revealed that home prices have appreciated by 5.6% over the last 12 months. The same report predicts that prices will continue to increase at a rate of 4.7% over the next year.

The bottom in home prices has come and gone. Home values will continue to appreciate for years. Waiting no longer makes sense.

2. Mortgage Interest Rates Are Projected to Increase 

Freddie Mac’s Primary Mortgage Market Survey shows that interest rates for a 30-year mortgage have hovered around 4.8%. Most experts predict that rates will rise over the next 12 months. The Mortgage Bankers Association, Fannie Mae, Freddie Mac and the National Association of Realtors are in unison, projecting that rates will increase in 2019.

An increase in rates will impact YOUR monthly mortgage payment. A year from now, your housing expense will increase if a mortgage is necessary to buy your next home.

3. Either Way, You are Paying a Mortgage

There are some renters who have not yet purchased homes because they are uncomfortable taking on the obligation of a mortgage. Everyone should realize that unless you are living with your parents rent-free, you are paying a mortgage – either yours or your landlord’s.

As an owner, your mortgage payment is a form of ‘forced savings’ that allows you to build equity in your home that you can tap into later in life. As a renter, you guarantee your landlord is the person building that equity.

Are you ready to put your housing cost to work for you?

4. It’s Time to Move on With Your Life

The ‘cost’ of a home is determined by two major components: the price of the home and the current mortgage rate. It appears that both are on the rise.

But what if they weren’t? Would you wait?

Look at the actual reason you are buying and decide if it is worth waiting. Whether you want to have a great place for your children to grow up, you want your family to be safer, or you just want to have control over renovations, maybe now is the time to buy.

If the right thing for you and your family is to purchase a home this year, buying sooner rather than later could lead to substantial savings.

Post navigation

Before & After: The Importance of Staging


There are a few things I recommend to all my clients who want to sell their home for top dollar. One of them is staging! Failing to “showcase” your home could keep your house on the market longer and may not sell for as much as its worth. First impressions are so important and really help potential buyers to imagine your house as their perfect house.

This charming house in Minnetonka took less than a week to stage and sold immediately over asking! With just a few contemporary pieces can make a night and day difference in the overall feel of a house.

For some more tips on low cost, high-value updates check out my other blog post.

5 Reasons It’ll Pay to Sell Your Home Early in 2018

blog title

Take a look at this blog post from realtors.com. To read the original post, click here.


By Holly Amaya, January 10, 2018

It’s been nearly a decade since the Great Recession delivered the worst housing crash in modern memory. But these days, the fallout feels squarely in the rearview mirror. Markets have bounced back with fervor, and confidence is skyrocketing: From Charlotte, NC, to Stockton, CA—and everywhere in between—homes are flying off the market at record prices, and buyers are still clamoring to get in the game.

One thing is clear: It’s a great time to be a seller.

“We’ve seen two or three years of what could be considered unsustainable levels of price appreciation, as well as an inventory shortage that resulted in a record low number of homes for sale across the country,” says Javier Vivas, director of economic research for realtor.com®.

In other words: Today’s buyers are exhausted. And in many cases that means they’re willing to sacrifice to get a toehold in the market.

Sounds like the stuff of seller’s dreams, right? But know this: If you plan to sell in 2018—and you want to unload your home quickly and for maximum money—your window of opportunity may be rapidly narrowing. Here’s why you should get moving ASAP.

1. Rates are still historically low, drawing buyers into the market

We may not be enjoying the rock-bottom interest rates of yore, but by historical standards, today’s 30-year mortgage rates—hovering just above 4%—are still low. And experts agree mortgage credit will remain relatively cheap for most of the year.

That means the getting’s still good for buyers—and, subsequently, for sellers looking to unload their homes.

But rates are on the rise, and it’s been widely predicted that they’ll reach 5% before year’s end. Buyers know that the longer they wait to buy, the more expensive it will be.

Roughly translated, that means you’d be wise to list your home earlier in the year, before more rate hikes kick in. Not only will you capture the market of buyers scurrying to close a deal, but if you’re buying after you sell, you’ll also benefit from those lower rates.

2. Inventory remains tight—and demand high

Simply put, there are more buyers than available homes—particularly in red-hot markets where land is scarce and it isn’t cheap to build.

And the housing shortage will likely get worse before it gets better: Realtor.com data predict inventory will remain tight in the first part of this year, reaching a 4% year-over-year decline by March.

Sellers, that means this is your opportunity to be wooed. Buyers, their choices limited, are going to great lengths (and making some major concessions) to win the house, says Katie Griswold, a Realtor® with Pacific Sotheby’s in Southern California.

“We’re in a very favorable seller’s market,” she says. “We’re seeing bidding wars—which push up prices—and buyers are submitting offers with very pro-seller terms, like forgoing the repair request or waiving the appraisal contingency.”

And cash investors are in the mix, too, accounting for 22% of all home sales transactions in November 2017 (up from 20% in October), according to the National Association of Realtors®.

Those cash buyers are snapping up homes in an already tight market and keeping some first-time buyers at bay (sorry, buyers!). But if you’re selling, you stand a better shot at an all-cash offer—one you just might be crazy to refuse.

Of course, there’s a catch: Inventory levels are predicted to begin rising in the fourth quarter, marking the first inventory gain since 2015 and setting the stage for more dramatic housing gains to come. So if you’re thinking of selling, start preparing now in order to walk away with a sweet paycheck.

3. Home prices are still increasing

From coast to coast, home prices continue to rise—which translates to more money in your pocket when you sell.

But the gains are predicted to be more moderate than in years past. Realtor.com data suggest a 3.2% increase year over year, after finishing 2017 with a 5.5% year-over-year increase.

Bottom line: You still stand to make a pretty profit if you sell this year, but the earlier you can list, the better off you’ll be.

4. People have more money in their pocket

Record levels of consumer confidence, low unemployment, and stock market surges are setting the stage for high home buyer turnout in 2018. For the first time since the 1960s, the Fed has projected that the unemployment rate will drop below 4%, and the domestic stock market is enjoying a nearly unprecedented rally.

The housing market is already reflecting this boom: Existing-home sales soared 5.6% in November 2017 (the most recent month for which data are available) and reached their strongest pace in almost 11 years, according to the NAR.

“Incomes are growing and people are finding better and more stable jobs,” Vivas says. Buyers “are feeling pretty good about (their) finances.”

And thanks to the GOP tax legislation, which nearly doubles the standard deduction, we’ll see fewer people itemizing, says National Association of Home Builders Chief Economist Robert Dietz.

“The income effect of that is that most people are getting a tax cut—which should help (buyer) demand,” Dietz says.

All of these factors combined mean more buyers could be on the hunt, with more money in their pockets to shell out on a home for sale—possibly yours!

5. Millennials are ready to commit

Millennials, often crippled by student debt, have been especially hampered by rising interest rates and high home prices.

But the aforementioned conditions are ripe in 2018 for these first-time buyers to take the plunge, and experts predict that millennials will make up a vital part of the buyer pool over the coming year: Millennials could account for 43% of home buyers taking out a mortgage in 2018 (a 3% year-over-year increase), according to realtor.com data.

“As people move into their 30s, they’re looking to move from renting to homeownership,” Dietz says. “And we predict that trend will continue even more this year.”

More home buyers flooding the market can only mean good things for sellers—at all price points.

Inventory Crunch Weighing On Sales Activity

Take a look at this blog post from the Minneapolis Association of Realtors from September 18th, 2017. To read the original post, click here.


 By Erin Milburn on Monday, September 18th, 2017

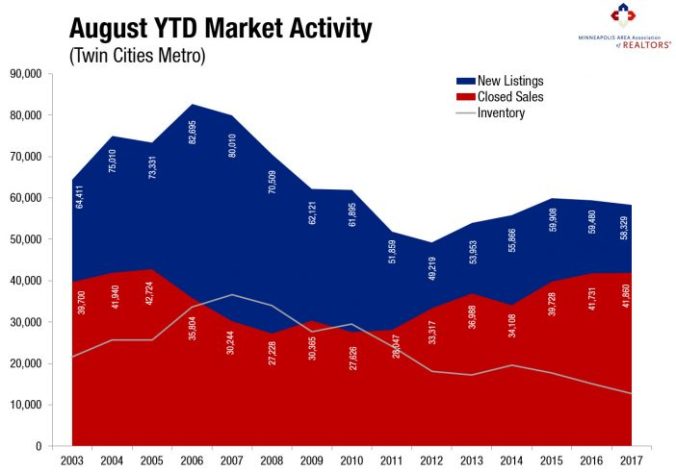
Minneapolis, Minnesota (September 18, 2017) – The Twin Cities housing market continues to show signs of high demand and short supply. While June 2017 marked an all-time home sales record for the Twin Cities, closed sales showed a year-over-year decline for the second consecutive month. The number of sellers listing their homes increased slightly, but that wasn’t enough to counteract the inventory drop. New listings increased 0.7 percent from last year to 7,264, and closed sales dipped 1.4 percent. The number of homes for sale decreased 16.7 percent to 12,602. Factoring out foreclosures and short sales, traditional new listings rose 2.4 percent while traditional closed sales increased 0.9 percent.

With many consumers competing for limited homes, prices remained firm, a trend that should continue into the fall and winter months. The median sales price rose 6.8 percent from last year to $252,000—a new monthly record for August. Home prices have now risen for the last 66 consecutive months or 5.5 years. At 48 days on average, homes went under contract 14.3 percent faster than last August. Sellers who do list are averaging 98.5 percent of their original list price, 0.6 percent higher than August 2016. The metro area has just 2.5 months of housing supply. Generally, five to six months of supply is considered a balanced market where neither buyers nor sellers have a clear advantage.

“The shortage of homes for sale is still driving this market,” said Cotty Lowry, Minneapolis Area Association of REALTORS® (MAAR) President. “It’s been the story for years, and it continues to influence prices, sales, market times and other indicators. The graphic illustrates how listings and sales have converged, leaving very little product lingering on the market.”

August-PR-Image-702x491

The shortage is most acute for entry-level homes. Well-priced, turnkey, well-presented listings are most competitive. Market times and absorption rates are tightest for homes priced under $200,000. For example, homes between $150,000 and $190,000 had 1.4 months of supply. As you move up the price ladder, the market is less competitive and better supplied. Homes priced between $500,000 and $1,000,000 boast 6.0 months of supply, while homes over $1,000,000 have a plentiful 12.3 months of supply.

The most recent national unemployment rate is 4.4 percent, though it’s 3.3 percent locally—the fourth lowest unemployment rate of any major metro area. A thriving and diverse economy has been conducive to housing recovery, as job and wage growth are key to new household formations and therefore housing demand. The Minneapolis–St. Paul region has a resilient economy with a global reach, a talented workforce, top-notch schools, exposure to the growing technology and healthcare fields, and a quality of life that’s enabled one of the highest homeownership rates in the country.

The average 30-year fixed mortgage rate has declined from 4.3 percent to 3.8 percent recently, still well below its long-term average of around 8.0 percent. Although at least one more rate hike was expected this year, the Fed is now focused on unwinding its large portfolio. Additional inventory is still needed in order to offset declining affordability brought on by higher prices and interest rates.

“We’re always impressed by how determined buyers are, despite the supply hurdle,” said Kath Hammerseng, MAAR President-Elect. “That said, prices are rising faster than incomes and builders are focusing on higher-end product further out while the demand is strongest for affordable product closer in.”

Nail Down the Cost of Your Roofing Project

roofing_cost_lp


When installing a new roof, the biggest decision you’re going to face (aside from choosing a roofing pro) is which materials to use. If you’re replacing an existing roof, your decision is easy — just match the current materials. But, if you’re building a new home, the debate over roofing materials can get a bit more complicated. Before jumping into the pros and cons of each material, consider the size and layout of your roof.

Not surprisingly, the size of your roof will play a large role in determining your overall budget. If you’re using a roofer, it’s helpful to understand how your pro will measure your roof. While many contractors base their estimates on square footage, roofing pros go by squares (each square is 100 square feet). The more squares, the more your project will cost.

Continue reading →

7 Pricing Myths to Stop Believing If You Ever Hope to Sell Your House

18ebed74c05176c6e1b088fa743023a5w-c0xd-w685_h860_q80

Pricing your own home is hard, what with all the history and hopes this magic number entails. Of course, you want to make a profit. Of course, all that money you spent installing a swimming pool or a half-bath will be recouped, because you’re leaving your digs in better shape than when you bought it, right? Right?

Well, not necessarily. Too many home sellers fall prey to myths about home pricing that seem to make sense at first, but don’t jibe with the reality of real estate markets today. To make sure you haven’t bought into any of this malarkey—since the buyers you’re trying to woo sure haven’t—here are some common pricing myths you’ll want to rinse from your brain so you kick off your home-selling venture with realistic expectations. It’s time to get real, folks!

1. You always make money when you sell a home

Sure, real estate tends to appreciate over time: The National Association of Realtors® estimates that home prices will jump 5% by the end of 2017 and continue rising 3.5% in 2018. But selling your home for more than you paid is by no means a given, and your return on investment can vary greatly based on where you live. Continue reading →

End of Summer To-Do List

Your End-of-Summer To-Do List

Labor Day unofficially marks the end of summer, but there’s still plenty of time to cross the remaining home projects off your summer to-do list. In fact, many homeowners wait until Labor Day even to start some of their biggest projects. So, you’re certainly not alone.

According to new HomeAdvisor data, these are the top six most popular end-of-summer projects homeowners are kicking off around Labor Day weekend!

Continue reading →